In a perfect world, we would all have numbers affixed to our foreheads providing an indicator of intelligence and lack thereof. Unfortunately, this is not only impractical, but would likely lead to discriminatory practices. Nevertheless, we have something known as The Consumer Confidence Index (CCI) which provides an aggregate public gullibility metric. Yesterday, The Conference Board reported May's CCI was 35% than that of April, indicating that the many of the 5000 households surveyed believed the government's Green Shoot PR campaign:
For certain, anyone within earshot of a teevee has heard the business media trumpeting the Green Shoot PR campaign. Any new economic indicator that is less negative is being proclaimed as positive and a confirmation that the recovery is at hand. (Considering all of the chicanery the government has condoned in the last six months, the accuracy of the most recent indicators is questionable.) The message is ubiquitous and apparently effective, demonstrating that the American public's appetite for propaganda is insatiable.
After all, didn't the teevee shill the following:
1. The Y2K non-apocalypse. 2. Electric deregulation 3. WMDs to justify the Iraq War. 4. 401k retirement plans in place of financial literacy. 5. The perpetual increase of housing prices and real estate speculation. 6. Consumption at the expense of saving. 7. Media consolidation 8. Diseases manufactured by the pharmaceutical industry, i.e. Restless Legs Syndrome. 9. A service economy based on truly unnecessary industries, instead of tangible good production. 10. Trade and immigration policies that led to a depressed standard of living in many parts of the country.
I would have thought that after seeing 40% of their retirement assets disappear, 30% of their home's value erode, 10% unemployment, an unprecedented $12T deficit, and the specter of massive tax increases, the public might start to question the MSM and whose interests it really serves. Apparently, the transient comfort provided by predatory optimism is preferable to reality. Thus, allow me to accomodate with the following inspirational excerpt from Time magazine titled, "Good Times Are Coming!," circa 2005:
Do we really consume too much and save too little? Fed data show that while debt has been rising, so has net worth, and debt as a percentage of net worth does not look overstretched. I am not unmindful of the risks. But I do think most of the analysis wildly oversimplified, particularly when the problem is identified as "imbalances," as though the economic system's natural state had been perturbed and until returned to balance it was out of whack.
My point is simple: this is just one of the things people are worrying about while the broad economic picture could hardly be better. General Electric just reported strong earnings and is confident of double-digit growth. IBM did the same. Citigroup chief financial officer Sallie Krawchek said recently on CNBC that it was "credit nirvana," the best environment they had seen in almost 15 years, and Citigroup raised its dividend another 10%.
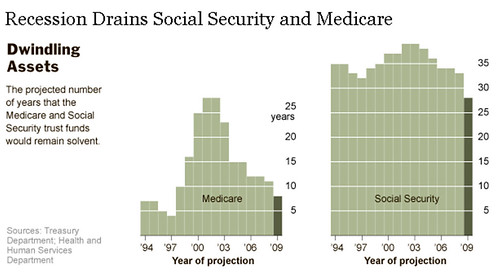
On May 12th, the New York Times published a story regarding the effects in the recession on the state of Social Security and Medicare. Significant deterioration of the financial health of these entitlement programs has raised questions as to their future viability and the need for reform. The NYT provided the following disturbing graphic which illustrates exactly how dire the situation has become: As you can clearly see the future of Medicare and Social Security is very bleak. The Treasury's 2009 projections indicate that Medicare only has only 1.5 little rectangles remaining, while SS has experienced a 20% year-over-year little rectangle reduction. Compounding matters, the little rectangles are turning black, which is a classic economic indicator of doomDOOM. The administration has proposed that health care cost cutting measures are the solution for Medicare:
The Treasury secretary, Timothy F. Geithner, said the only way to keep Medicare solvent was to “control runaway growth in both public and private health care expenditures.” And he said Mr. Obama intended to do that as part of his plan to guarantee access to health insurance for all Americans. But if cost controls do not produce the expected savings, Congress is likely to find it difficult to preserve benefits without increasing taxes.
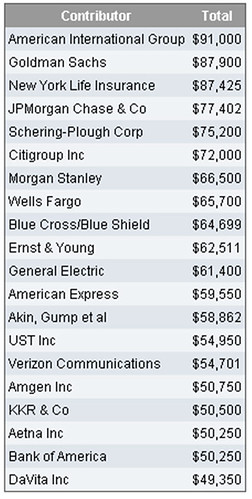
Using Austrian Polygonal Differential Analysis common sense on the following historical health care industry campaign contribution charts from OpenSecrets.org , the probability of future health care cost reductions fall somewhere in the range of notahopeinhell and 0. In reality, the health care and insurance industries are taking a page from the TARP playbook, where the specter of crisis.is being used to justify corrupt legislation. The health care lobby graciously agreed to reduce cost growth (not level, but rate of change) by 1.5%, yielding a projected savings of $2T over the next ten years. In exchange for this triviality, the insurance industry will receive a massive subsidy in the form of artificial demand creation; legally mandated health insurance for all US citizens in 2013.
This was the masterstroke of Senate Finance Committee's chairman, Max Baucus. Chairman Baucus spent long hours at the Roundtable to Discuss Reforming America’s Health Care Delivery System "hammering out" out the particulars with representatives from Blue Cross, Aetna, and the Business Roundtable. And when I say "hammering out," what I mean is selling legislation and the public interest for campaign contributions: Lifetime contributions to Sen. Max Baucus via Opencecrets.org.
Yesterday, someone (who thinks this blog should be funnier??) sent me a link to The Bing Blog, which is the creation of, the aptly named, Stanley Bing. In Bing's most recent post, Things That Will Survive, he declares that the current recovery is genuine and prognosticates about what the new growth will look like. Since Stanley Bing isn't actually a real person and doesn't seem to have much economic training, he's more apt to be correct than your standard, celebrity econotard. I won't regurgitate his post, but it gave me an idea: Wouldn't it be clever to post a series of predictions, so that in a year I can look back and see that, I too, can't differentiate my ass from third base.
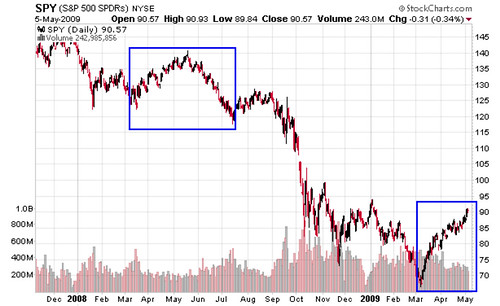
Prediction I: This rally is an extended sucker's rally. This isn't much of a stretch considering that 70% of the GDP is consumer based and somewhere between 10-15% of these consumers are now jobless. However, I am reminded of a time when I was all in on fairly out of the money puts. At the time, the government and the MSM were lying about the state of the economy, despite obvious evidence to the contrary. The experts called the bottom and proclaimed that up was the only direction remaining. I spent weeks mentally willing the destruction of the stock market, to no avail. For a month, I questioned whether I'd arrived at a very wrong and expensive conclusion about the economy's direction. That month was March of 2008:
Thus, Spring of 2009 seems hauntingly familiar, except I hold no derivative positions. Sure enough, it charts similarly, as well. Increasing pricing on decreasing volume seems to be the portent of doom. (3/08-7/08, Thanksgiving 08-Feb 09). I am attempting to become a reformed speculator, but synthetically shorting crap like WYN @ 10 is so very, very tempting (-WYN HB, +WYN HV (protection), +WYN TB). We'll see if discipline prevails.
Prediction II: 401(k)/IRA redemptions and loans will be restricted. Over 5M Americans are unemployed and that's likely a conservative estimate. Moreover, many of the unemployed/underemployed have been so for months now. As the personal savings rate actually went negative during the bubble and the collective home equity piggy bank has been smashed, defined contribution funds are increasingly likely to be drained. Moreover, people are beginning to wise up to the fact that the 401(k) may well have been the greatest scam ever perpetuated by Wall Street, next to Donald Trump's hair. Thus, there has been a steady outflow of cash from equity mutual funds over the last year. If you compare the market capitalization of the NYSE to defined contribution plan/IRA equity assets, you'll discover the Evil Whose Name Can Never Be Spoken: Much of Wall Street is Main Street. While this topic could easily fill another 10 posts, if not an entire blog, let it suffice to say that DC plan redemptions en masse would cripple the stock market. Notice how Obama's campaign promise to ease penalties on 401(k) hardship redemptions has never been revisited. As the stock market goes, so does Wall Street, so this will not be allowed to happen
Prediction III: Municipalities will default in record numbers and won't get bailouts resembling what Wall Street received. Recently, I've been looking at the budgets of various local governments across the country. During the credit bubble, many ran deficits, not unlike their citizens. Unfortunately, municipalities generate revenue primarily through real estate tax, sales tax, and, less often, income tax, which are all falling at a significant rate. I expect that they'll attempt to issue more bonds, but at some point credit rating deterioration will induce unservicable rates. I don't expect significant federal assistance either, due to Wall Street's complete ownership of Congress and the Treasury. Instead, bankrupt cities will have privatization rammed down their throats, because little is more profitable than a monopoly on products with inelastic demand, like water and policing.
Prediction IV: Free markets will become even more farcical with consolidation. I don't think there is a company in existence that is interested in truly free trade. In practice, the phrase "free trade" has come to stand for using competition to decrease input costs, while attempting to reduce competitive forces affecting output prices. A developing nation's poverty will continue to be viewed as its greatest resource, to the detriment of American workers who insist on an "extravagant" standard of living. Wage and benefit claw backs will increase, while price fixing becomes even more blatant, as competing companies consolidate. In the last decade, we've seen little along the lines of anti-trust legislation or enforcement and I expect this to worsen. Within 5 years, I can envision the same style of collusion, demonstrated by the petroleum industry under Bush, to be adopted by producers of goods with low elasticity, like food, medicine, and energy.
Prediction V: This blog will not get any funnier. Truly humorous blogs are a rarity, while commonality is a staple here. Thus, never doubt my grave sincerity when I make proclamations like; the only asset class that is guaranteed to continually appreciate is Golden Girls memorabilia, which constitutes the basis for its use as a global currency standard. Really, I think I may have been mistaken for someone else.
So there you have it. In a year, I, hopefully, can look back at this post and say, "What a moron. I need to trade my computer in for an Etch-A-Sketch." In the mean time, I'll be working on my Canadian residency visa and hoarding Bea Arthur posters by the gross.
On Thursday, the Senate defeated amendment (Amdt. 1014) to the Helping Families Save Their Homes Act of 2009 (S.896). The amendment proposed by Sen. Dick Durbin, IL, provided a mechanism for troubled homeowners to avoid foreclosure. Specifically, before a homeowner entered bankruptcy, they would first have to meet with the lender and give the lender the opportunity to offer a loan modification, such that the homeowner's debt/income ratio would be reduced to 31% or less. If the homeowner refused, the bankruptcy court would not be allowed to modify the loan. If the lender refused to offer a workout, the bankruptcy court would have the power to make the aforementioned modifications to the loan terms. In other words, the banks would be forced to offer legitimate workout plans that reduce principal, as opposed to the current, farcical loan modifications that we've seen consistently fail.
"These bankers who brought us into this crisis are literally shunning and stiff-arming the people who are facing foreclosure,” said Senator Richard Durbin of Illinois, sponsor of the legislation and the chamber’s second-ranking Democrat.........Democrats led by Durbin had sought a compromise on the measure with JPMorgan Chase & Co., Wells Fargo & Co., Bank of America Corp., the American Bankers Association and Financial Services Roundtable. The lenders that scuttled the negotiations are “surviving today because of taxpayers’ dollars,” Durbin said. The three banks he named received $95 billion in U.S. aid.
The financial industry rationalized its position by claiming that Durbin's measure would destabilize the housing market. This logic makes little sense, because it's hard to envision anything more destabilizing to the housing market than a wave of foreclosures. The real goal of the banking industry is to make bankruptcy as unappealing as possible to troubled debtors, as demonstrated by the uber-sleazy Bankruptcy Reform of 2005. Diana Olick of CNBC made a telling statement:
One insider very close to the process on the Hill tells me, "If you asked me four months ago, I would have said cram down was a lock."
Four months ago, bailouts were a fairly novel stench and the public was starting to realize that the financial industry controlled much of the government. Obama and Congress performed an impressive charade by publicly lambasting bank CEOs and the SEC, but Mario Cuomo is the only official to actually attempt to strike blood. Banksters even delayed making the campaign contributions, which are the fuel of our present democratic circumvention. As I've said before, this economic crisis was bought and paid for with campaign contributions. They were the root cause and have created a situation where a non-voting entity, like the ABA, has more political power than the electorate. Four months later, the contributions have brazenly resumed in earnest, no doubt the result of demographic studies that show that the American public has returned to its uneasy slumber. By allowing the continuation of corporate governance, it is clear that the Profit Gods will be appeased at our collective expense. This constitutes an unsustainable situation that I sincerely believe will end badly.
Thursday, the Attorney General of New York released a letter summarizing the testimony (provided below) of Ken Lewis, Bank of America's CEO, regarding the acquisition of Merrill Lynch. Lewis's testimony describes the strong arm tactics used by Paulson, Bernanke, and federal regulators to continue the acquisition despite the fact that BAC's due diligence determined that Merrill was likely to realize a $14 billion loss for the 4th quarter of 2008. The extent of Merrill's deterioration was revealed to Lewis on 12/14/08 and he subsequently contacted then Treasury Secretary Paulson to indicate BAC's intent to invoke the Material Events Change (MAC) clause in the acquisition contract to void the deal. What followed was a series of threats by Paulson and Bernanke to fire Lewis and the board of directors, if the merger didn't proceed as planned.
We know that the board was aware of the threats by the meeting minutes attached as Exhibits B and C. Paulson and Bernanke made verbal assurances to Lewis that the resulting losses from Merrill would be covered by future bailout disbursements, but they refused to give a written assurance for fear of disclosure (Exhibits C and D).As you probably know, the merger was completed and BAC reported over $15B in losses directly attributable to Merrill in the 4th quarter. Clearly, Lewis and BAC's board was derelict in its duty to shareholders. In fact, it can be argued (and it should be in court) that shareholders were deceived by senior BAC management so that said management could retain their lucrative positions. Who did Paulson, Bernanke, and BAC leave holding the bag? The usual suspects; Fidelity, Vanguard, State Street, T Rowe Price, and other retirement fund managers. In other words, us. Again.
As we're in the midst of the Crap Rally That Will Not Die, I can only wonder who else the Fed and Treasury have put the boots to. Their actions with BAC were blatantly illegal, so it's hard to remove much from consideration. I have grave doubts about shadowy Fed-surrogates, behind grassy knolls, buying S&P500 futures, since this could be detected in historical volume data. Perhaps, Tyler Durden of Zero Hedge has it right when he says that hedge funds and GS are the real Plunge Protection Team, flitting in and out of low volume markets to manipulate prices. However, Occam's Razor rarely disappoints, so I'm inclined to look towards the $3.5T slush fund that is perfect for this very thing. This slush fund contains the dumbest money ever, has little transparency, won't stand the test of redemption for years, and is controlled by few, some of whom are even TARP recipients.
Most equity retirement (401(k)/IRA) mutual funds claim a maximum stock allocation of 80%, but I'd wager that they are quite a bit north of that. In fact, I wouldn't be shocked to find that some of the $3.8T of money market funding hadn't slipped the leash and found its way into the equity markets. Lewis testified and Paulson corroborated that the government verbally promised to "fill the holes," so I don't think my tin foil hat is terribly shiny here. Nevertheless, this is purely speculation from an entirely unqualified observer, so I encourage you to peruse the Investment Company Institute's archive of mutual fund data and annual Factbook, the EBRI's Databook, and Federal Reserve Board's Flow of Funds Z.1 and see what's what.
STATE OF NEW YORK OFFICE OF THE ATTORNEY GENERAL 120 Broadway New York, NY 10271 ANDREW M. CUOMO Attorney General (212) 416-8050 April 23, 2009 The Honorable Christopher 1. Dodd, Chairman u.s. Senate Committee on Banking, Housing, and Urban Affairs 534 Dirksen Senate Office Building Washington, DC 20510 The Honorable Barney Frank, Chairman House Financial Services Committee Democratic Staff 2129 Rayburn House Office Building Washington, DC 20515 Re: Mary L. Schapiro, Chairman U.S. Securities and Exchange Commission Office of the Chairman 100 F Street, NE Washington, DC 20549 Ms. Elizabeth Warren, Chair Congressional Oversight Panel 732 North Capitol Street, NW Rooms C-320 and C-617 Mailstop: COP Washington, DC 20401 Bank of America - Merrill Lynch Merger Investigation Dear Chairpersons Dodd, Frank, Schapiro and Warren: I am writing regarding our investigation of the events surrounding Bank of America's merger with Merrill Lynch late last year. Because you are the overseers and regulators of the Troubled Asset Relief Program ("TARP"), the banking industry, and the Treasury Department, we are informing you of certain results of our investigation. As you will see, while the investigation initially focused on huge fourth quarter bonus payouts, we have uncovered facts that raise questions about the transparency of the TARP program, as well as about corporate governance and disclosure practices at Bank of America. Because some matters relating to our investigation involve federal agencies and high-ranking federal officials charged with managing the TARP program, we believe it is important to inform the relevant federal bodies of our current findings. We have attached relevant documents to this letter for your review. On September 15,2008, Merrill Lynch entered into a merger agreement with Bank of America. The merger was negotiated and due diligence was conducted over the course of a tumultuous September 13-14 weekend. Time was of the essence for Merrill Lynch, as the company was not likely to survive the following week without a merger. The merger was approved by shareholders on December 5, 2008, and became effective on January 1,2009. The week after the shareholder vote - and days after Merrill Lynch set its bonuses Merrill Lynch quickly and quietly booked billions of dollars of additional losses. Merrill Lynch's fourth quarter 2008 losses turned out to be $7 billion worse than it had projected prior to the merger vote and finalizing its bonuses. These additional losses, some of which had become known to Bank of America executives prior to the merger vote, were not disclosed to shareholders until mid-January 2009, two weeks after the merger had closed on January 1,2009. On Sunday, December 14,2008, Bank of America's CFO advised Ken Lewis, Bank of America's CEO, that Merrill Lynch's financial condition had seriously deteriorated at an alarming rate. Indeed, Lewis was advised that Merrill Lynch had lost several billion dollars since December 8, 2008. In six days, Merrill Lynch's projected fourth quarter losses skyrocketed from $9 billion to $12 billion, and fourth quarter losses ultimately exceeded $15 billion. Immediately after learning on December 14,2008 of what Lewis described as the "staggering amount of deterioration" at Merrill Lynch, Lewis conferred with counsel to determine if Bank of America had grounds to rescind the merger agreement by using a clause that allowed Bank of America to exit the deal if a material adverse event ("MAC") occurred. After a series of internal consultations and consultations with counsel, on December 17,2008, Lewis informed then-Treasury Secretary Henry Paulson that Bank of America was seriously considering invoking the MAC clause. Paulson asked Lewis to come to Washington that evening to discuss the matter. At a meeting that evening Secretary Paulson, Federal Reserve Chairman Ben Bernanke, Lewis, Bank of America's CFO, and other officials discussed the issues surrounding invocation of the MAC clause by Bank of America. The Federal officials asked Bank of America not to invoke the MAC until there was further consultation. There were follow-up calls with various Treasury and Federal Reserve officials, including with Treasury Secretary Paulson and Chairman Bernanke. During those meetings, the federal government officials pressured Bank of America not to seek to rescind the merger agreement. We do not yet have a complete picture of the Federal Reserve's role in these matters because the Federal Reserve has invoked the bank examination privilege. Bank of America's attempt to exit the merger came to a halt on December 21, 2008. That day, Lewis informed Secretary Paulson that Bank of America still wanted to exit the merger agreement. According to Lewis, Secretary Paulson then advised Lewis that, if Bank of America invoked the MAC, its management and Board would be replaced: [W]e wanted to follow up and he said, 'I'm going to be very blunt, we're very supportive on Bank of America and we want to be of help, but' -- as I recall him saying "the government," but that mayor may not be the case - "does not feel it's in your best interest for you to call a MAC, and that we feel so strongly," -- I can't recall ifhe said "we would remove the board and management if you called it" or ifhe said "we would do it if you intended to." I don't remember which one it was, before or after, and I said, "Hank, let's deescalate this for a while. Let me 2 talk to our board." And the board's reaction was of "That threat, okay, do it. That would be systemic risk." In an interview with this Office, Secretary Paulson [argely corroborated Lewis's account. On the issue of terminating management and the Board, Secretary Paulson indicated that he told Lewis that if Bank of America were to back out of the Merrill Lynch deal, the government either could or would remove the Board and management. Secretary Paulson told Lewis a series of concerns, including that Bank of America's invocation of the MAC would create systemic risk and that Bank of America did not have a legal basis to invoke the MAC (though Secretary Paulson's basis for the opinion was e,ntirely based on what he was told by Federal Reserve officials). Secretary Paulson's threat swayed Lewis. According to Secretary Paulson, after he stated that the management and the Board could be removed, Lewis replied, "that makes it simple. Let's deescalate." Lewis admits that Secretary Paulson's threat changed his mind about invoking that MAC clause and terminating the deal. Secretary Paulson has informed us that he made the threat at the request of Chairman Bernanke. After the threat, the conversation between Secretary Paulson and Lewis turned to receiving additional government assistance in light of the staggering Merrill Lynch losses. Lewis spoke with individual Board members after his conversation with Secretary Paulson. The next day, December 22,2008, the Board met and was advised of Lewis's decision not to invoke the MAC. The minutes of that meeting listed the key points of Lewis's calls with Secretary Paulson and Chairman Bemanke: (i) first and foremost, the Treasury and Fed are unified in their view that the failure of the Corporation to complete the acquisition of Merrill Lynch would result in systemic risk to the financial system in America and would have adverse consequences for the Corporation; (ii) second, the Treasury and Fed state strongly that were the Corporation to invoke the material adverse change ("MAC") clause in the merger agreement with Merrill Lynch and fail to close the transaction, the Treasury and Fed would remove the Board and management of the Corporation; (iii) third, the Treasury and Fed have confirmed that they. will provide assistance to the Corporation to restore capital and to protect the Corporation against the adverse impact of certain Merrill Lynch assets: and (iv) fourth, the Fed and Treasury stated that the investment and asset protection promised could not be provided or completed by the scheduled closing date of the merger, January 1, 2009; that the merger should close as schedu[ed, and that the Corporation can rely on the Fed and Treasury to complete and deliver the promised support by January 20, 2009, the date scheduled for the release of earnings by the Corporation. The Board Minutes further state that the "Board clarify[ied] that is [sic] was not persuaded or influenced by the statement by the federal regulators that the Board and management would be 3 removed by the federal regulators if the Corporation were to exercise the MAC clause and failed to complete the acquisition of Merrill Lynch." Another Board meeting was held on December 30,2008. The minutes of that meeting stated that "Mr. Lewis reported that in his conversations with the federal regulators regarding the Corporation's pending acquisition of Merrill Lynch, he had stated that, were it not for the serious concerns regarding the status of the United States financial services system and the adverse consequences of that situation to the Corporation articulated by the federal regulators (the "adverse situation"), the Corporation would, in light of the deterioration of the operating results and capital position of Merrill Lynch, assert the material adverse change clause in its merger agreement with Merrill Lynch and would seek to renegotiate the transaction." Despite the fact that Bank of America had determined that Merrill Lynch's financial condition was so grave that it justified termination of the deal pursuant to the MAC clause, Bank of America did not publicly disclose Merrill Lynch's devastating losses or the impact it would have on the merger. Nor did Bank of America disclose that it had been prepared to invoke the MAC clause and would have done so but for the intervention of the Treasury Department and the Federal Reserve. Lewis testified that the question of disclosure was not up to him and that his decision not to disclose was based on direction from Paulson and Bernanke: "I was instructed that 'We do not want a public disclosure. '" Secretary Paulson, however, informed this Office that his discussions with Lewis regarding disclosure concerned the Treasury Department's own disclosure obligations. Prior to the closing of the deal, Lewis had requested that the government provide a written agreement to provide additional TARP funding before the close of the Merrill Lynch/Bank of America merger. Secretary Paulson advised Lewis that a written agreement could not be provided without disclosure. Lewis testified that there was no discussion with the Board about disclosure to shareholders. However, on the night of December 22, 2008, Lewis emailed the Board, "I just talked with Hank Paulson. He said that there was no way the Federal Reserve and the Treasury could send us a letter of any substance without public disclosure which, of course, we do not want." The December 30 Board meeting minutes further reflect that Bank of America was trying to time its disclosure of Merrill Lynch's losses to coincide with the announcement of its earnings in January and the receipt of additional TARP funds: "Mr. Lewis concluded his remarks by stating that management will continue to work with the federal regulators to transform the principles that have been discussed into an appropriately documented commitment to be codified and implemented in conjunction with the Corporation's earning [sic] release on January 20, 2009." It also bears noting that while no public disclosures were made by Bank of America, Lewis admitted that Bank of America's decision not to invoke the MAC clause harmed any shareholder with less than a three year time-horizon: 4 Q. Wasn't Mr. Paulson, by his instruction, really asking Bank of America shareholders to take a good part of the hit of the Merrill losses? What he was doing was trying to stem a financial disaster in the financial markets, from his perspective. From your perspective, wasn't that one of the effects of what he was doing? Over the short term, yes, but we still thought we had an entity that filled two big strategic holes for us and over long term would still be an interest to the shareholders. What do you mean by "short-term"? Two to three years. A. Q. A. Q. A. Notably, during Bank of America's important communications with federal banking officials in late December 2008, the lone federal agency charged with protecting investor interests, the Securities and Exchange Commission, appears to have been kept in the dark. Indeed, Secretary Paulson informed this Office that he did not keep the SEC Chairman in the loop during the discussions and negotiations with Bank of America in December 2008. As this crucial recovery process continues, it is important that taxpayers have transparency into decision-making. It is equally important that investor interests are protected and respected. We hope the information herein is useful to you in your federal regulatory and oversight capacities and we remain ready to assist further in any way. We also note that we have been coordinating our inquiry with the Special Inspector General for the Troubled Asset Relief Program, whose investigation also remains open. Andrew M. Cuomo Attorney General of the State of New York cc: Neil Barofsky Special Inspector General Troubled Asset Relief Program 5
I may well be a 13 year old and/or a dog. I'm infinitely more interested in promoting critical thinking and evaluation, than credibility. The outsourcing of analysis to pundits, demagogues, and "experts" was no small contributor to our current situation.






 Posts